

NOTE: This post is about health insurance and a departure from my usual topics of music and songwriting in the Midwest. As I continue to learn more through personal experience, I will occasionally share insights for readers as we all try our best to navigate a challenging system. I also encourage readers to leave feedback. The comments section of this article is full of firsthand insights.
With premiums often as low as $0, Medicare Advantage is a popular choice for an estimated 250,000+ Iowans. The Annual Enrollment Period (AEP) officially concluded on December 7th; if you committed to using Medicare Advantage in 2026, it’s time to review your plan to make sure you understand its key components. Understanding your coverage (and its gaps) can help prevent unfortunate financial consequences, especially in light of today’s astronomical health care costs.
Unlike traditional Medicare, Medicare Advantage plans are operated by private corporations. The system is complex and full of nuances. As a licensed insurance agent and a seasoned family caregiver, I want to share my knowledge and experience to help you make smart, safe decisions. This article will explore three major questions that all Medicare Advantage enrollees need to know. We will evaluate these questions through the lens of our real-world experience with my wife’s uncle Pete.
THREE BIG QUESTIONS FOR MEDICARE ADVANTAGE (MA) ENROLLEES:
Am I prepared to use doctors and facilities that are only in-network?
What are my maximum out-of-pocket costs?
Do I have prescription drug coverage in my plan?
Big Question #1: Will my health care be in-network?
Understanding the difference between “in-network” and “out-of-network” with your Medicare Advantage plan is vital. It can mean the difference between full coverage and financial catastrophe. Many providers are no longer accepting plans from certain companies, so it’s critical that you make sure that your doctors and facilities are compatible with your plan. Some medical institutions are better at sharing this information than others, but it’s important to understand that the onus is on the consumer.
For example, The Iowa Clinic has the following posted directly on their website.
When you click on the “View Insurance” button you will find this information on the next page with various other insurance information.
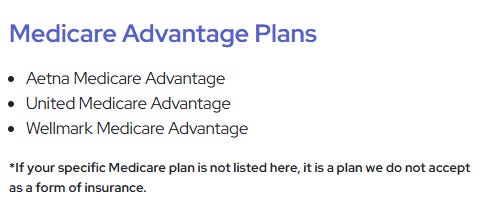
Per their note at the bottom, “If your specific Medicare plan is not listed here, it is a plan we do not accept as a form of insurance.” In other words, The Iowa Clinic and their dozens of providers and specialists have opted out of the majority of MA plans in the market. If your insurance company isn’t Aetna, United Healthcare or Wellmark, your insurance would NOT be accepted by The Iowa Clinic that provides “40+ specialties and close to 20 different locations around the Des Moines metro area”.
The trend is for healthcare providers to opt out of many MA plans. Back in September, The Messenger reported the following in their article, “Iowa Specialty Hospital to stop accepting certain Medicare Advantage plans,” specifically quoting Chief Nursing Officer Beth Carder about the change, “When we have patients on Medicare Advantage plans, many of the plans require pre-authorization for services. Families are confused and frustrated because their patient isn’t authorized for those services,” Carder said. “Some have ended up paying privately, which can get pricey as well.”
She noted multiple cases where doctors and nurses recommended continued care, but insurers determined there was not medical necessity for the services. Chief Compliance Officer Reagan Swisher said many patients don’t realize how different Medicare Advantage is from traditional Medicare.
“Many families think that when they have Medicare Advantage … it’s Medicare, because of that Medicare Advantage name,” he said. “Health insurance is difficult to understand on a good day.”
UnityPoint Health has yet to take the drastic steps of The Iowa Clinic, yet they strongly encourage patients to review their specific plans. Below is the statement they provided me upon request of guidance to this “in-network” question.
“UnityPoint Health understands the relationship between a patient and their healthcare provider is a critical component of the overall healthcare experience. We encourage all patients to review their health insurance plan options for 2026 to make sure it covers your preferred doctors and prescriptions. UnityPoint Health is in-network with a number of Medicare Advantage plans in central Iowa and is ready to care for you when you need us.”
Bottom line: you must do your due diligence in knowing your care will be covered.
For those of you following along on Uncle Pete’s wellness journey, he received life-saving care from The Iowa Clinic and UnityPoint Health from sepsis in 2025. His primary care doctor is at The Iowa Clinic, as are several of his specialists. He was initially treated in the Methodist Emergency Room, transferred to Methodist West, and UnityPoint at Home continued his care in our home. He very much wants to continue his care with these providers with whom he has established a professional and trusted relationship.
Big Question #2: What are my maximum out-of-pocket (MOOP) costs?
When comparing 2025 and 2026 Medicare Advantage plan options, please be mindful that “one of the most significant financial changes coming in 2026 involves the maximum out-of-pocket (MOOP) limit for Medicare Advantage plans. The Centers for Medicare & Medicaid Services (CMS) is increasing this ceiling, which caps the amount that beneficiaries pay for covered services in a year. While the exact limit varies depending on the specific plan you choose, the federal maximum is expected to increase by several hundred dollars compared to 2025 levels. This increase means that seniors could potentially pay more in copays, coinsurance, and deductibles before reaching the point where their plan covers 100% of additional costs. For those with chronic conditions or who anticipate needing significant medical care, this change could represent a meaningful increase in annual healthcare expenses. It’s crucial to carefully review your plan’s specific MOOP limit and budget accordingly for the coming year, especially if you’re managing multiple health conditions that require regular care. Understanding the consequences of a potential extended medical stay is important (SavingAdvice.com).”
All available plans can be found on the SHIIP site below, as instructed “For more information on plans available in Iowa, use the link below to view and download our consumer guide 2025 Medicare Advantage Plans in Iowa or 2026 Medicare Advantage Plans in Iowa for the upcoming year.”
Like thousands of Iowans, Pete’s Medicare Advantage plan is administered through United Healthcare. Below is a side-by-side comparison between the 2025 and 2026 versions.
2025 UHC Complete Care IA-5-C-SNP HMO-POS (H5253-180)
Yearly Maximum Out-of-Pocket: $3900
Monthly Premium: $0
Inpatient Hospital: $475/day for days 1-6, $0 for days 7-unlimited.
Skilled Nursing Care: $0 each day for days 1-20; $203/day for days 21-100.
Medicare Prescription Drug Coverage: Yes.
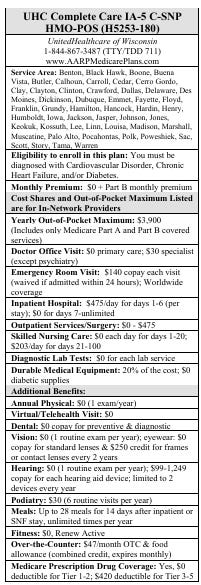
2026 UHC Complete Care IA-5-C-SNP HMO-POS (H5253-180)
Yearly Maximum Out-of-Pocket: $5900
Monthly Premium: $27 + Part B monthly premium
Inpatient Hospital $550/day for days 1-5, $0 for days 6-unlimited
Skilled Nursing Care: $0 each day for days 1-20, $218/days 21-100.
Medicare Prescription Drug Coverage: Yes.
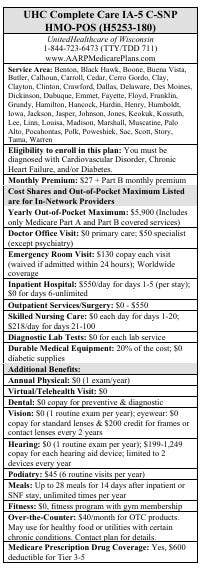
While 2025 was an atypical health year for Pete, we know that the likelihood of more serious care increases as we age. Given Shakespeare’s adage from The Tempest “what’s past is prologue,” we are exploring ways to be more prepared in 2026 for a health crisis.
One common misperception with Medicare Advantage plans is that you can’t have supplemental insurance as protection. While it’s true you can’t sign up for what’s commonly referred to as a Medicare Supplement, there are available policies that reimburse for hospital stays, ambulance rides, treatment in skilled nursing facilities and other care received.
For example, if Pete were to have the same incident in 2026, we could be more prepared with a hospital indemnity plan designed to reimburse for specific maximum out-of-pocket costs. Knowing that Pete’s 2026 MOOP will now be $5900, he could sign up for a policy with me that reimburses him $990/night for 6 nights in the hospital for $83.33/mo., knowing he’d be fully protected while in the hospital decreasing the stress of financial concerns while convalescing. While it’s impossible to predict the future, and it’s unlikely we’ll have an exact repeat of last year, with rising health care costs and the fact that he had a sizeable out-of-pocket cash hit in 2025, at least subsidizing such a big hit expense feels wise. For example, at $47.60/mo., Pete could have coverage for 4 nights in the hospital at $600/night and $400 per ambulance ride. This supplemental insurance plan would cover about half of the cash needed and not require as many nights in the hospital. Sometimes as we age, there’s less upside in rolling the dice on our health. Finding $50-$100 in your monthly budget might be much easier than to locate $5900 at once.
Big Question #3: Will my plan cover my prescription drugs?
Another misconception is that all Medicare Advantage plans include drug coverage. While most do, some don’t, so if you need prescription drugs, check that the plan has Part D built in or plan to add a separate drug plan if switching back to Original Medicare.
THE BIG PICTURE: Healthcare costs are continuing to rise. Examples like Pete’s are both encouraging and frustrating. On the one hand, the system absolutely saved his life. If not for his Medicare Advantage plan, he would have been in a real world of hurt both physically and financially. On the other hand, the costs feel out of control for regular folks and the system is making the consumer bear more of them year after year. The 2026 MA plans are higher across the board at a time when many people have less income and more affordability issues.
If you discover that your MA plan is problematic because you can’t see your trusted provider, don’t fret just yet because even though the Annual Enrollment Period is over as of December 7th, you can still likely improve your situation. If you’re already in a Medicare Advantage plan, you have another opportunity during the Medicare Advantage Open Enrollment Period from January 1 to March 31, 2026. At this time, you can switch to another Medicare Advantage plan or go back to Original Medicare, possibly adding a separate Part D plan.
Below are more insights I pulled together as I was doing research for this article. There are a lot of insightful resources available out there. In addition, if you live in Iowa, Kansas or Missouri, I can assist you. You can set an appointment here and learn more. I specialize in alternatives to long-term care, caregiver, cancer and hospital indemnity insurance policies.
Other Resources and Insights:
If you live in Iowa, “SHIIP is a free, objective and confidential service. SHIIP is offered through the Iowa Insurance Division. SHIIP offers one-on-one assistance, counseling, and education to Medicare beneficiaries, their families, and caregivers to help them make informed decisions about their care and benefits. SHIIP services support people with limited incomes, Medicare beneficiaries under the age of 65 with disabilities, and individuals who are dually eligible for Medicare and Medicaid.” Here’s the link to start a session with a counselor.
Medicare in Iowa Snapshot
The Centers for Medicare & Medicaid Services (CMS) reported the following information on Medicare trends in Iowa for the 2026 plan year:
A total of 680,584 Iowa residents are enrolled in Medicare.
There are 63 Medicare Advantage plans available in Iowa for 2026, compared with 75 plans in 2025.
The average monthly Medicare Advantage plan premium changed from $12.38 in 2025 to $15.11 in 2026.
All Iowa residents with Medicare have access to a Medicare Advantage plan with a $0 premium.
In 2026, there are 11 stand-alone Medicare Part D prescription drug plans available in Iowa, and the lowest monthly premium for a stand-alone Part D plan is $4.70.
17.2% of people with a stand-alone Part D plan get Extra Help.
Here is a link to the official government booklet aptly titled: Your Guide to Medicare Drug Coverage. In 2026, the annual out-of-pocket limit for Medicare enrollees on drugs covered by Part D plans will increase slightly from $2,000 to $2,100. If the plan includes a prescription drug benefit, you still need to be sure your drugs are covered by the plan and your pharmacy is in the plan’s network. SHIIP can help you run a comparison to see which plans cover your drugs at the lowest cost.
Many people with a Medicare Advantage plan get prescription coverage through their plan, but you must make sure to enroll in a plan that includes prescription drug coverage. If you join a standalone Part D (drug plan), you will be automatically disenrolled from your Medicare Advantage plan and returned to Original Medicare Parts A & B. If you have Original Medicare benefits or a Medicare Cost Plan, you can join a standalone Medicare Prescription Drug Plan. Your out-of-pocket costs will depend on the plan’s premium, whether the plan has a yearly deductible, the plan’s copayments or coinsurance, and if your drugs are covered on the plan’s formulary. Individuals who receive help with their Medicare drug plan costs (through Extra Help) will continue to pay reduced costs if they enroll in a Medicare Advantage plan that includes drug coverage. To compare Medicare Advantage plan drug benefits, you can go to www.medicare.gov and select “Find Plans Now.” SHIIP/SMP counselors are also available to help you compare plans.
What to Do if Your Hospital Drops Your Medicare Advantage Plan - NerdWallet
NOTE: All annual paid subscribers to Chip Happens will now receive a copy of my 2025 CD compilation, Twenty-Five, that includes 25 original songs. To those of you that have already upgraded and purchased the CD, my sincerest of thanks! You are a critical component of making Chip Happens! You can upgrade your subscription here and receive a copy for your physical music collection. If you are only in the market for the CD, it is available here for $25. CD art and design were completed by my amazing and talented wife, Jen Albright. To learn more about Chip and his personal experience with caregiver insurance, please click here.
Thanks for this, Chip, my friend. But I still don't know what the fuck I'm doing with my Medicare plan. And I have a Ph.D. I think they want us confused, on purpose.
The cheap premiums often entice people. As a pharmacist, my perception is that these plans are rarely worth it. There are far too many unexpected surprises as you try to navigate the process of receiving healthcare. What you save in premiums you often pay for in surprises later.